Being healthy, rarely sick, and uninsured in Arizona feels like a safe bet, until an ER visit, a car accident, or an unexpected diagnosis turns one bad day into a debt you carry for years. Arizona Health Insurance exists precisely for that gap between feeling fine and staying financially protected.
By Higby Health Insurance Team, Health Insurance Advisors
Why Being Healthy Doesn't Cancel Out the Need for Coverage
Feeling fine is not the same as being financially protected. Most Arizonans who skip health insurance do it because they rarely see a doctor, not because they've weighed the actual risk. But the entire logic of insurance is built around the fact that healthy people, statistically, still get into car accidents, still develop appendicitis, and still receive a cancer diagnosis with no warning at all. Arizona's uninsured rate has stayed persistently higher among younger, healthier adults than any other age group, according to state coverage reports, largely because this population assumes coverage is a cost for people who are already sick, not a way to access affordable care while they're still healthy. That's the position anyone healthy, rarely sick, and uninsured in Arizona is in today: manageable risk, until it isn't.
Does Being Young and Healthy Mean You Don't Need Health Insurance?
Age lowers your average risk, it does not remove it. A healthy 27-year-old is exactly the person an ER visit or a broken leg from a hiking accident can turn into a five-figure bill overnight. Community data consistently points to a single serious event, not chronic illness, as what pushes uninsured young adults into medical debt. Being young and healthy usually lowers your monthly premium, but it doesn't affect whether an accident can happen to you.
The Real Cost of Staying Healthy, Rarely Sick, and Uninsured in Arizona
Without insurance, a single trip to the emergency room in Arizona can run into five figures before you've even been admitted. A broken bone that requires surgery, imaging, and a two-night hospital stay routinely tops tens of thousands of dollars in billed charges, the list price hospitals charge patients with no insurer negotiating rates on their behalf. Health insurance coverage doesn't just pay bills, it also negotiates them down to a fraction of what an uninsured patient is billed directly.
What Happens If a Rarely-Sick Person Gets Seriously Hurt or Diagnosed With Something Unexpected?
This is the scenario that catches healthy people off guard. A rarely-sick person who skips a routine screening for a few years can be diagnosed with cancer at a later, more expensive stage, or can survive a car accident only to face months of physical therapy and follow-up care with no coverage behind any of it. Arizona hospitals are generally required to treat emergencies regardless of a patient's ability to afford care, but treated does not mean paid for. The bill still arrives, and it becomes a personal debt, not an insurance claim.
The Real Rules: Penalties, Legality, and What Arizona Requires
Is There Still a Penalty for Being Uninsured in Arizona?
No. The federal tax penalty for not having health insurance was reduced to zero starting in 2019, and Arizona has not enacted its own state-level mandate penalty the way a few other states have. That said, the financial risk described above never went away, it simply moved from a guaranteed penalty to a possible, much larger one.
Is It Illegal to Not Have Health Insurance in Arizona?
No, it is not illegal. Arizona does not require residents to carry health insurance, and there's no legal consequence for going without it. The confusion usually traces back to the Affordable Care Act's original individual mandate, which applied a federal penalty nationwide before Congress zeroed it out. Going uninsured today is legal, it's just financially unprotected.
Low-Cost Coverage Options for People Who Rarely Use Care
Plans exist specifically for people who don't expect to use much care in a given year, and pairing the right one with the right subsidy is where most of the savings on health coverage comes from. An Individual Health Insurance plan bought through the ACA Marketplace, with premium tax credits applied, is often far cheaper than the sticker price you'd see browsing plans without checking eligibility first. Federal subsidies are based on income, not health status, so a healthy applicant qualifies for the same savings as anyone else. Every Marketplace plan is required to publish a Summary of Benefits and Coverage, and the main content of that document spells out exactly what's covered before you owe a single premium dollar.
What's the Cheapest Health Insurance for a Healthy Person in Arizona?
For most healthy Arizonans, the cheapest realistic option is a subsidized bronze or catastrophic Marketplace plan, not going uninsured. Community health centers and free clinics can help with routine visits, but they don't cover a hospitalization, surgery, or a cancer treatment plan. Current Marketplace data shows subsidized bronze premiums running well below unsubsidized rates for adults under 40 in most Arizona counties, which is why comparing actual after-subsidy pricing matters more than assuming coverage is unaffordable.
How Much Does a Catastrophic or Bronze Plan Cost in Arizona Versus Staying Uninsured?
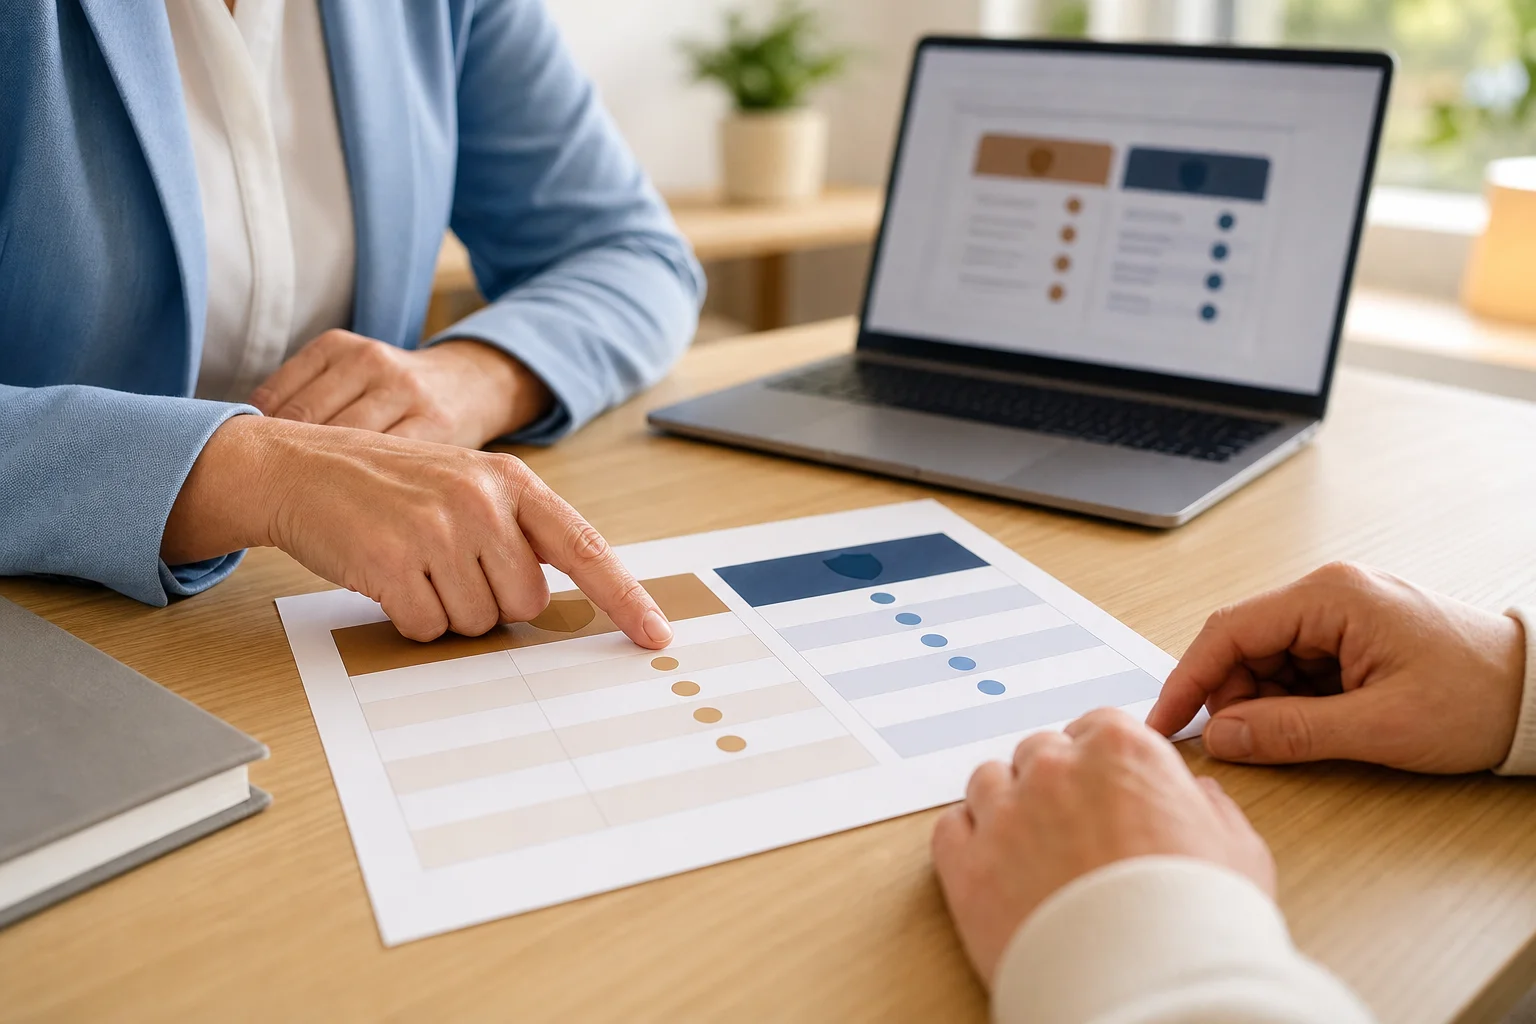
A subsidized bronze plan for a healthy adult in Arizona commonly runs far less per month than most people expect once premium tax credits are applied, while a catastrophic plan, available to people under 30 or older adults with a hardship exemption, trades a lower premium for a higher deductible. Compare either one to the alternative: one uninsured emergency room visit can cost more than several years of premiums combined. The math almost never favors staying uninsured once you actually run the numbers.
Is a Catastrophic Health Plan a Good Fit for Someone Who Is Rarely Sick?
Often, yes. Catastrophic plans are built for people who rarely use care but still want protection against a worst-case event, the same logic that leads healthy professionals across industries toward catastrophic coverage instead of skipping insurance altogether. These plans must offer essential health benefits after the deductible is met, including preventive services at no cost.
What Preventive Care and Screenings Do You Give Up by Skipping Coverage?
Under the Affordable Care Act, Marketplace and most employer plans cover preventive services like annual physicals, blood pressure checks, cholesterol panels, and age-appropriate cancer screenings at no additional cost. Going without insurance means many people skip the screenings that catch a problem while it's still cheap and treatable, then end up diagnosed later, sicker, and facing a far larger bill.
Can I Just Pay Out of Pocket Instead of Buying a Health Plan?
For routine care, sometimes. A basic checkup or urgent care visit is manageable in cash for a lot of healthy people, which is part of why going without insurance feels safe. The problem is that paying out of pocket only works until it doesn't: a single surgery, a multi-day hospital stay, or an ongoing diagnosis like cancer treatment can run into six figures, more than most American families keep on hand. Carrying a lower-premium bronze or catastrophic plan for the big events, while paying cash for small visits, is a far more realistic strategy than hoping nothing serious happens.
Frequently Asked Questions
Do I really need health insurance if I rarely get sick?
Yes. Health insurance protects against the event you can't predict, not the visits you already expect. Rarely getting sick lowers your odds of a large bill in any given year, it doesn't remove the possibility, and a single accident or diagnosis can cost far more than years of premiums combined.
Is there a tax penalty for being uninsured in Arizona in 2026?
No. The federal individual mandate penalty was reduced to zero in 2019, and Arizona has not added its own state penalty. There's no tax consequence for going without coverage, but the medical debt risk from an uncovered emergency is unchanged and can be far larger than any penalty ever was.
What's the biggest financial risk of skipping health insurance when you're healthy?
The biggest risk isn't routine care, it's a low-probability, high-cost event: a serious accident, an unexpected cancer diagnosis, or a hospitalization. These bills routinely reach five or six figures for uninsured patients, since there's no insurer-negotiated rate reducing what's owed.
Can healthy people qualify for lower-cost health insurance plans in Arizona?
Yes. Premium tax credits are based on household income, not health status, so a healthy applicant qualifies for the same federal subsidies as anyone else. Bronze and catastrophic plans are typically the lowest-cost options for people who rarely use medical care.
Talk to an Advisor Before You Renew Your Bet on Staying Healthy
Being healthy, rarely sick, and uninsured in Arizona is a choice you can make with real numbers instead of a guess, and most people are surprised at what affordable health care actually costs once subsidies are applied. Contact our advisors for a free comparison of bronze, catastrophic, and marketplace plans based on your age, income, and county.
